How “Funds For You” Can Help When Life Throws You a Curveball
Picture this: it’s a regular Tuesday morning, and your car has decided it’s had enough of functioning. The mechanic hits you with a quote that makes your stomach drop. Or maybe your dog swallowed something he shouldn’t have, and now there’s an astronomical vet bill staring you down. Life’s great at throwing these kinds of “surprises,” isn’t it?
But here’s the thing—most emergencies don’t care if your bank account’s ready or if your credit score hasn’t been Instagram-worthy lately. And that’s where personal loans, like the ones offered by Funds For You, can swoop in and save the day. These aren’t just loans—they’re lifelines. Lifelines that can cover medical bills, car repairs, or even give you the boost you need to consolidate some high-interest credit card debt.
Not all personal loans are created equal, though. Some options are helpful and flexible—a hand up when you’re struggling—while others (looking at you, payday loans) can trap you in an endless cycle of debt. So, let’s break down how to handle this tricky world of borrowing, even if your credit score isn’t doing cartwheels right now.
Why Your Credit Score Is the Real Star of the Show
If you’ve ever applied for a loan—or even thought about it—you’ve probably heard people throw around the term “credit score” like it’s some magical number in the sky. And honestly? It kind of is.
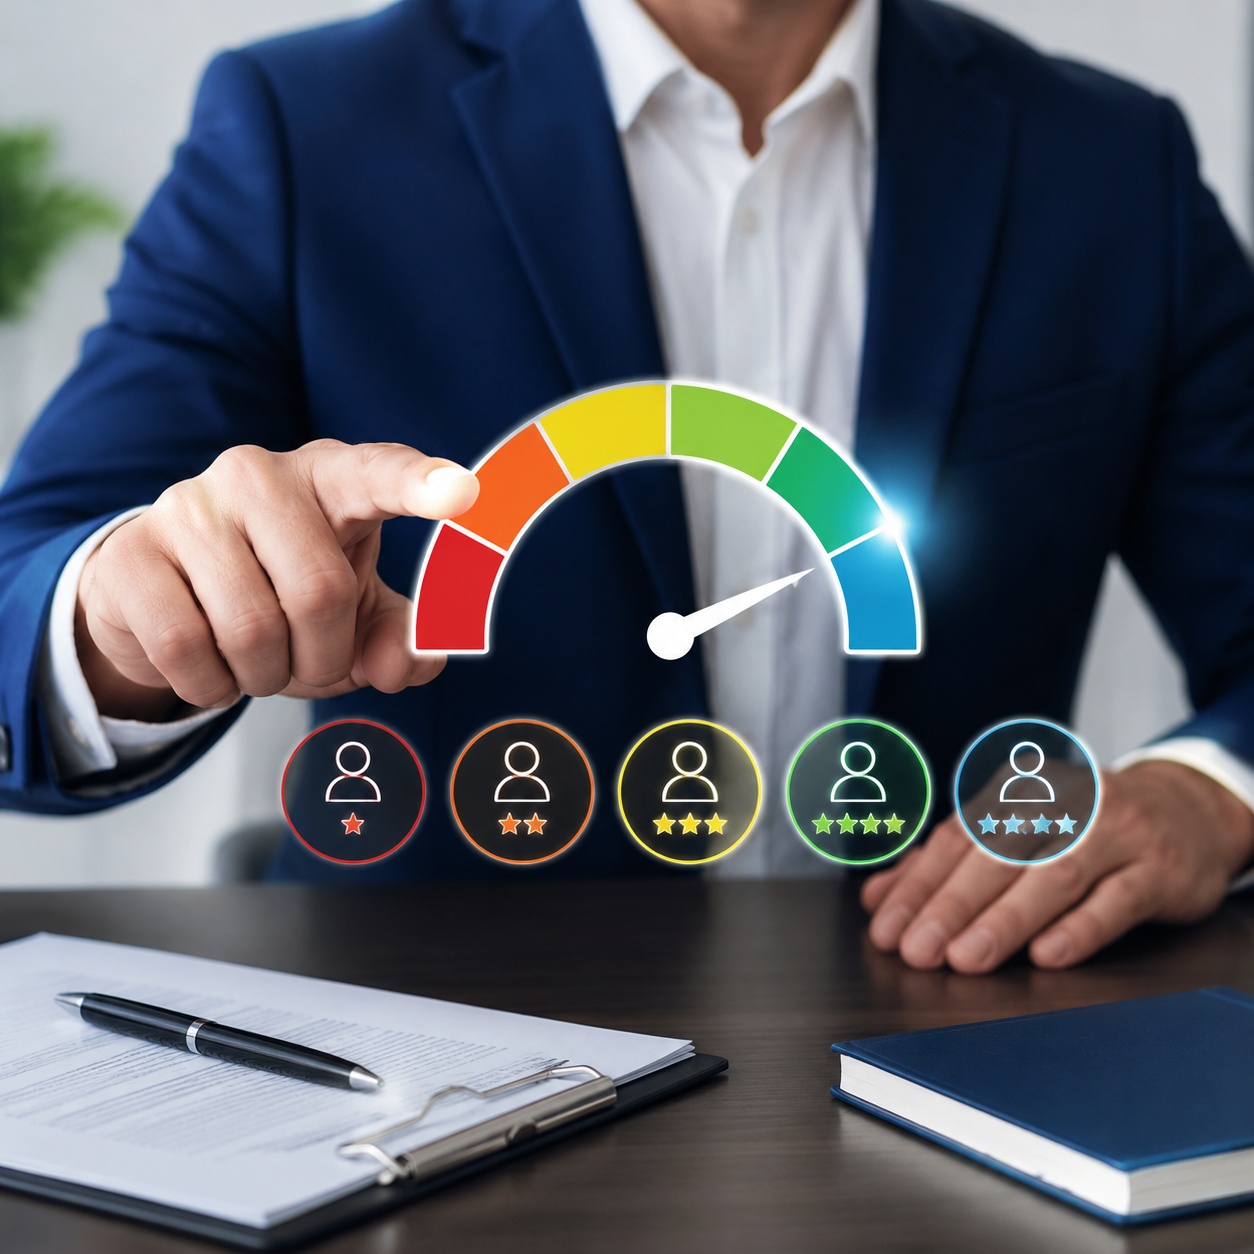
Your credit score is a three-digit snapshot of how risky you are to lenders. Basically, it tells them, “Hey, can I trust this person with my money or nah?” And let me be blunt: your score dictates what kind of deal you’ll get when you borrow.
Got a score between 800 and 850? Congrats, you’re in elite territory. Lenders practically trip over themselves to offer you low-interest loans. About 82.8% of borrowers in this range get approved—which makes sense because you’re the human equivalent of a risk-free investment. But if you’re rocking a sub-580 score? That’s when it gets messy. Only a handful of lenders (I found 13 advertised offers when I looked this up) are willing to work with credit that low.
And while there are options for bad credit loans, these usually come with sky-high interest rates. It’s like trying to dig yourself out of a hole while someone keeps throwing dirt back in. This is why keeping an eye on—and improving—your credit score matters.
But hey, life happens. If your credit score took a nosedive during a rough patch, you’re not alone. I’ve been there too, staring at those numbers like a failing grade on a test. The key is knowing that you’ve still got options.
Breaking Down Personal Loan Rates (And Why They Vary So Much)
Here’s a jaw-dropper: the same $5,000 loan can cost one person $5,500 and another person $8,000, depending on their credit score and loan terms. How? It’s all in the APR—annual percentage rate.
But let’s back up for a second. Most people think of loan interest as the only “extra cost” of borrowing, but APR also includes fees, like origination or administrative charges. It’s the number you really want to watch because it’s the big picture.
For example, someone with good credit might qualify for Funds For You personal loans with rates starting as low as 6.99%—that’s what they call an “easy application loan with low interest.” But if you’re in the not-so-great-credit club, your APR could climb into the double-digit range.
It’s not just your credit score that affects rates, though. Things like the loan term, the amount you’re borrowing, and even what you plan to use the money for can play a part. Want the lowest possible rates? Shoot for shorter loan terms and polish up that credit score.
Which Lenders Are Best For Your Credit Score?
Let’s be real: while having excellent credit makes borrowing a breeze, most of us aren’t walking around with perfect numbers. So, here’s a breakdown of personal loan options depending on where you stand with your credit.
If Your Credit Is Excellent (740-850)
Congrats! You’re living in lender heaven. Tons of options are available to you because you’re considered low-risk. You’ll likely snag competitive personal loan rates and flexible terms. Funds For You personal loans are an excellent option in this tier—low rates, no hidden fees, and, if you’re approved, you can get funds as fast as the same day.
Good Credit? (670-739)
You’re in great shape, which means you’ll still qualify for most “prime” loans out there. Your rates might be a little higher than the top tier, but you can still expect pretty affordable loan solutions. Just make sure to shop around and compare offers—because even a 1% difference can add up.
Credit’s…Not So Great? (580-669)
Here’s where things get trickier. You’re not in the danger zone, but lenders see you as more of a risk. The good news? There are still “easy application loans with low interest” tailored to people in this range. And Funds For You offers options that work specifically with borrowers who might need a little extra wiggle room.
Below 580: The (Temporary) Danger Zone
If your score falls here, don’t panic—you’re not doomed to predatory payday loans. Yes, options are limited. The loans you qualify for will likely have high APRs, but Funds For You has flexible terms for people in this category, too. Plus, some lenders offer secured loans, which let you use your car or savings as collateral to score better rates.
Storytime: That One Time I Faced A Financial Disaster
A couple of years ago, I got hit with a $2,800 medical bill that I just…didn’t have. No emergency fund. Mediocre credit. Staring down a bill collector is not an experience I’d recommend to anyone.
Enter: a personal loan. After some serious research—and panicking—I went with a lender that worked with my less-than-perfect credit score. The interest wasn’t great (11%), but it bought me time to pay off the bill in manageable chunks over 18 months.
Looking back, I wish I’d had more financial cushion or known about other resources, like interest-free university emergency loans (did you know UC Berkeley offers up to $1,720 for students in a jam?) or tailored loans like those from Funds For You. Their flexibility around credit scores could have saved me a pretty penny.
Your Credit Score Isn’t Final—Here’s How to Boost It
I can’t tell you how many times I’ve heard people say, “There’s no way I can fix my credit—there’s just too much damage.” Look, I get that feeling. But here’s the thing: improving your score is possible. It just takes time and a little strategy.
- Pay off small debts first. Ever heard of the debt snowball method? Knock out your smallest balances first to grab those quick wins and gain momentum.
- Never miss a bill. Payment history makes up 35% of your credit score. Even if you’re only making minimum payments, consistency is everything.
- Keep credit utilization low. If you’re maxing out all your cards, your score’s going to tank. Aim to keep usage under 30% of your available credit.
And here’s a tidbit most people forget: if your score is dragging and you’ve got a loved one with stellar credit, ask if they’d consider adding you as an authorized user. It’s a hack that can give your score a serious boost—just be sure you trust each other.
So What’s the Plan When You’re Sweating an Emergency Expense?
Look, none of us plan to need emergency loans. That’s the whole point of an emergency—it comes out of nowhere. But what you can plan for is how you’ll handle it when it happens.
First, build that emergency fund. Experts say it should cover 3-6 months of expenses. I know, that number sounds enormous—especially if you’re not in a great place financially right now. So start small. Even $500 can make a huge difference when you’re staring down an unexpected car repair.
But if saving ahead of time just isn’t an option and you find yourself cash-strapped, take a deep breath. Look for trusted personal loan providers in the US, like Funds For You, that offer quick funding for unexpected expenses without burying you in predatory terms. And if you’ve got bad credit, don’t get discouraged—consider secured loans, co-borrowers, or credit repair before diving into high-interest waters.
Life’s going to throw curveballs—probably more than we’d like, honestly. And when the unexpected happens, you’ve got choices. A personal loan isn’t always the perfect solution, but with providers like Funds For You, it can be the lifeline that helps you stay afloat without feeling like you’re drowning in debt.
So don’t wait for your car to break down or the washing machine to dump water all over your laundry room floor (true story, by the way). Start planning now. And if you’re already in the thick of it? You’ve got options—more than you might think.