Funds For You: Is This the Personal Loan You’ve Been Waiting For?
Let’s start with the obvious: money problems don’t wait for a convenient time. Your car breaks down on the way to work. A surprise medical bill slides into your inbox like it isn’t going to ruin your week. Or maybe you just need to cover something exciting—like your sister’s last-minute destination wedding in Costa Rica (yes, this happened to me). Whatever the case, sometimes you don’t have savings to fall back on. A personal loan can be the lifeline you need.
But here’s the tricky part about borrowing money: the options out there range from helpful to absolutely predatory. Ever heard of payday loans with their 300% APR? Or the slick “buy now, pay later” apps that whisper sweet nothings about monthly payments but could wreck your budget if you miss one? That’s why finding affordable loan solutions—like the ones offered by Funds For You personal loans—can make a world of difference when you’re in a bind.
Now, not all personal loans are created equal. Some have great rates but take forever to fund (less than ideal when you’re staring down an urgent medical bill). Others boast quick cash but smack you with sky-high interest. Let’s break it all down: real options, real talk, no fluff.
Your Credit Score Isn’t Just a Number—It’s the Whole Show
Look, I know it feels like your credit score is this distant, judgmental little goblin that doesn’t reflect who you really are. But when it comes to personal loans, lenders are laser-focused on it. Your score dictates more than just approval odds—it decides your interest rate, how much you can borrow, and, sometimes, how quickly you can get the funds.
Here’s a quick stat for you: if your credit score is 800 or above (a.k.a. unicorn-level credit), you’ve got an approval rate of 82.8% for personal loans. But if your score dips below 580? You’re down to 13 offers—and those offers often come with eye-watering rates north of 25%. That’s the price of a low score.
What does this mean in dollar terms? Say you need to borrow $5,000 for… I don’t know, replacing your A/C during a summer heatwave. Someone with a stellar credit score might snag an APR of 6% and end up paying about $5,150 over two years. Meanwhile, someone with a lower score could be staring at a 25% APR and a total repayment of over $6,650. All for the same $5,000 loan.
It’s not about judging your financial past—it’s just how the system works. But the good news? Providers like Funds For You offer easy application loans with low interest rates for folks with decent credit, and they’re upfront about their terms. That transparency matters.
How Loan Rates Are Decided (Hint: It’s Not Just About You)
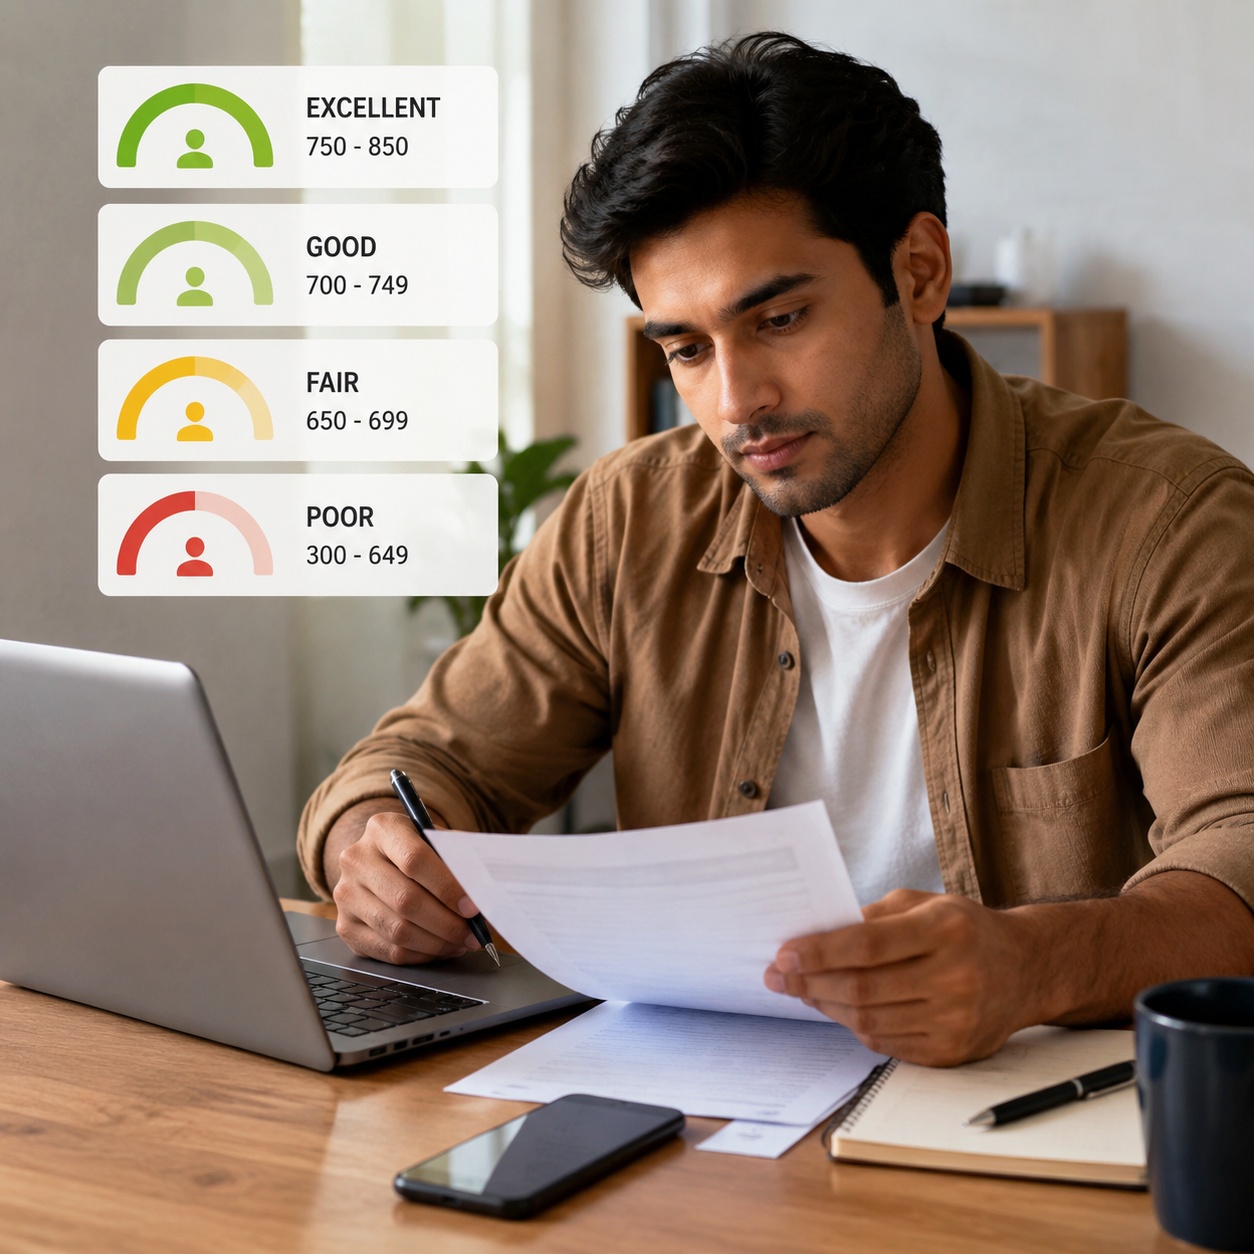
Speaking of interest rates, do you ever wonder how lenders decide what you’ll pay? Sure, your credit score plays a huge role—better scores mean less risk for them, so they can afford to lend you money for cheap. But there are other factors too, like current economic conditions (we’re all at the mercy of the Fed, aren’t we?) and even the type of loan you need.
Emergency loans, for example, usually come with slightly higher rates compared to a loan for, say, home renovations. Why? Because lenders know you’re borrowing quick funding for unexpected expenses. You’re under pressure and really need cash fast. That causes risk to spike, which bumps up the rate.
Then there’s the loan term to consider. Longer terms often mean lower monthly payments, but you’ll pay more in interest over time. It’s a bit like those meal subscription services—you could pay $120 upfront for three months of meals, or spread it out to $45/month and spend more in the long run. There’s no right or wrong answer; it’s about what you can handle right now.
With Funds For You, the good thing is they emphasize clarity. You know what you’re getting into with them—no hidden fees or ridiculous gotchas. It’s not a magic wand (you’ll still pay interest), but they keep it straightforward, which can’t be said for every lender.
Best Personal Loan Options for Every Credit Score
Here’s the fun part: comparing options. Not all lenders cater to the same customers, so you must go where you’re most likely to succeed. It’s a little like dating—don’t waste your time with someone looking for something else.
-
Great Credit (740 and above):
If your credit’s a slam dunk, congrats! Practically every lender will want to throw money at you. Some of the best options include SoFi and Marcus by Goldman Sachs. They’ll give you competitive personal loan rates, no fees, and flexible terms. -
Good to Fair Credit (670–739):
This is the sweet spot for providers like Funds For You personal loans. They’re a trusted personal loan provider in the US, offering affordable loan solutions that still keep rates competitive for this range. Borrowers here tend to fall between the “gold” and “bronze” tier—solid, but not perfect. Rates will vary, but you’ll have solid options. -
Bad Credit (Under 580):
Okay, this one’s tricky. But it’s not impossible. You’ll have a tougher time locking in good APRs, and a lot of the offers you’ll see might feel like a trap. But Funds For You and a handful of others specialize in low credit score loans. They might impose stricter conditions—think lower loan limits or proof of steady income—but that’s common across the board. Just make sure you’re not biting off more than you can chew.
Tips for Improving Your Loan Approval Chances (Even with Crummy Credit)
Bad credit doesn’t have to be the end of the line. If you’re serious about getting approved—and at a tolerable rate—here are some tips I’ve told my friends and tried myself:
-
Fix Your Credit (If You Can): This sounds like a no-brainer, but hear me out. I had a friend who disputed a couple of errors on her credit report and added 30 points in under two months. No magical hacks—just combing through the reports on annualcreditreport.com and writing letters to the credit bureaus.
-
Use a Co-Borrower: Got a financially stable friend or family member who’s willing to cosign? This can turn your loan from a hard “nope” into a confident “yes.” Just make sure it’s someone willing to take that risk for you, because they’ll be responsible if you can’t pay.
-
Start Small: Don’t go overboard and try to borrow $20,000 right out the gate if your credit’s shaky. Start with smaller loans and build up a repayment history. Think of this like a workout—nobody starts benching 250 pounds on Day 1.
Worst case? If your credit’s in the basement and you need emergency money today, some universities (hi, UC Berkeley) offer interest-free emergency loans up to $1,720 for students. It’s worth exploring.
When (and Why) Funds For You Makes Sense
Here’s where I see Funds For You fitting into your game plan: if you’ve got decent credit and need money quickly without diving into predatory territory. They’re not a catch-all—if you’ve got pristine credit, you can probably find a slightly lower APR elsewhere. But for most of us in the real world, where credit scores are a work in progress, their easy application loans with low interest provide that middle ground between sketchy high-interest options and unicorn-level lending.
The application process? Smooth. You’re not stuck scanning a hundred documents or waiting weeks for funding. It’s one of those quick funding for unexpected expenses type of solutions. And as someone who’s had to tackle an emergency root canal bill two days before rent was due, I can tell you how important that kind of speed is.
The Bottom Line (No, Really)
There’s no sugarcoating it—navigating personal loans can feel like trying to wade through quicksand. But if you know where to look (and what questions to ask), you can find legitimate, helpful options.
Funds For You personal loans stand out for their balance of accessibility and transparency. They’re not about to magically solve all your financial problems, but they can be a trusted bridge to get you from “Oh crap, I need money” to “Whew, that’s handled.”
At the end of the day, your financial health is a long game. Whether it’s building your credit, playing it safe with emergency funds, or borrowing smart when you’re in a tight spot, every decision matters. Start where you are. And when you’re ready, Funds For You could be a solid step in the right direction.