
Need Cash Fast? How Viva Payday Loans Can (and Can’t) Help
Running out of money before your next paycheck is a special kind of stress, isn’t it? Rent’s due, the car’s making a noise that sounds expensive, and payday might as well be a year away. If you’ve been in this spot (and trust me, I’ve been there), you understand the desperation that can set in. For folks with shaky credit—bad credit, no credit, or just one-too-many “oops” moments—finding funds quickly can feel impossible.
That’s where something like Viva Payday Loans, and other companies offering short-term cash solutions, come into the picture. Sounds promising, right? But here’s the thing about payday loans: they’re kind of like a fire extinguisher for your wallet. Essential in emergencies but risky if you rely on one every time you burn your toast. So, before you dive in, let’s talk about how these loans work, what alternatives are out there, and what you can do to protect yourself from a financial downward spiral.
Fast Cash When Credit’s Not on Your Side
First things first— bad credit payday loan options exist for a reason. Everyone hits bumps in the road, and lenders like Viva Payday Loans cater to those of us without a gold-star credit score. Unlike traditional lenders that demand a 700-plus credit score and a mountain of paperwork, payday loan companies operate differently. Need quick cash before payday? They’ll often skip the credit check and focus on your ability to repay the loan from your upcoming paycheck.
I’ll admit, there’s something refreshing about not having your financial past held against you. A bad score—or lack of credit history—doesn’t mean you’re irresponsible. It might just mean you hit some tough times. And when you’re in a bind, the speed and simplicity of same day funding options can feel like a lifeline.
But here’s my nudge. Just because the option is there doesn’t mean it’s the best one. Payday loans are expensive—like “scream-into-your-pillow once you see the fees” expensive. The average payday loan APR is around 400%. And yes, you read that right. Four. Hundred. Percent.
Picture it this way: Imagine you’re grabbing a quick bite to eat because you’re starving. You spot two options. One stand sells a $5 hot dog. The other sells the same hot dog for $20, but they’ll hand it to you faster. That’s basically the choice you’re making when you opt for a payday loan over other emergency borrowing options.
Emergency Loans: Payday Loans vs. Everything Else
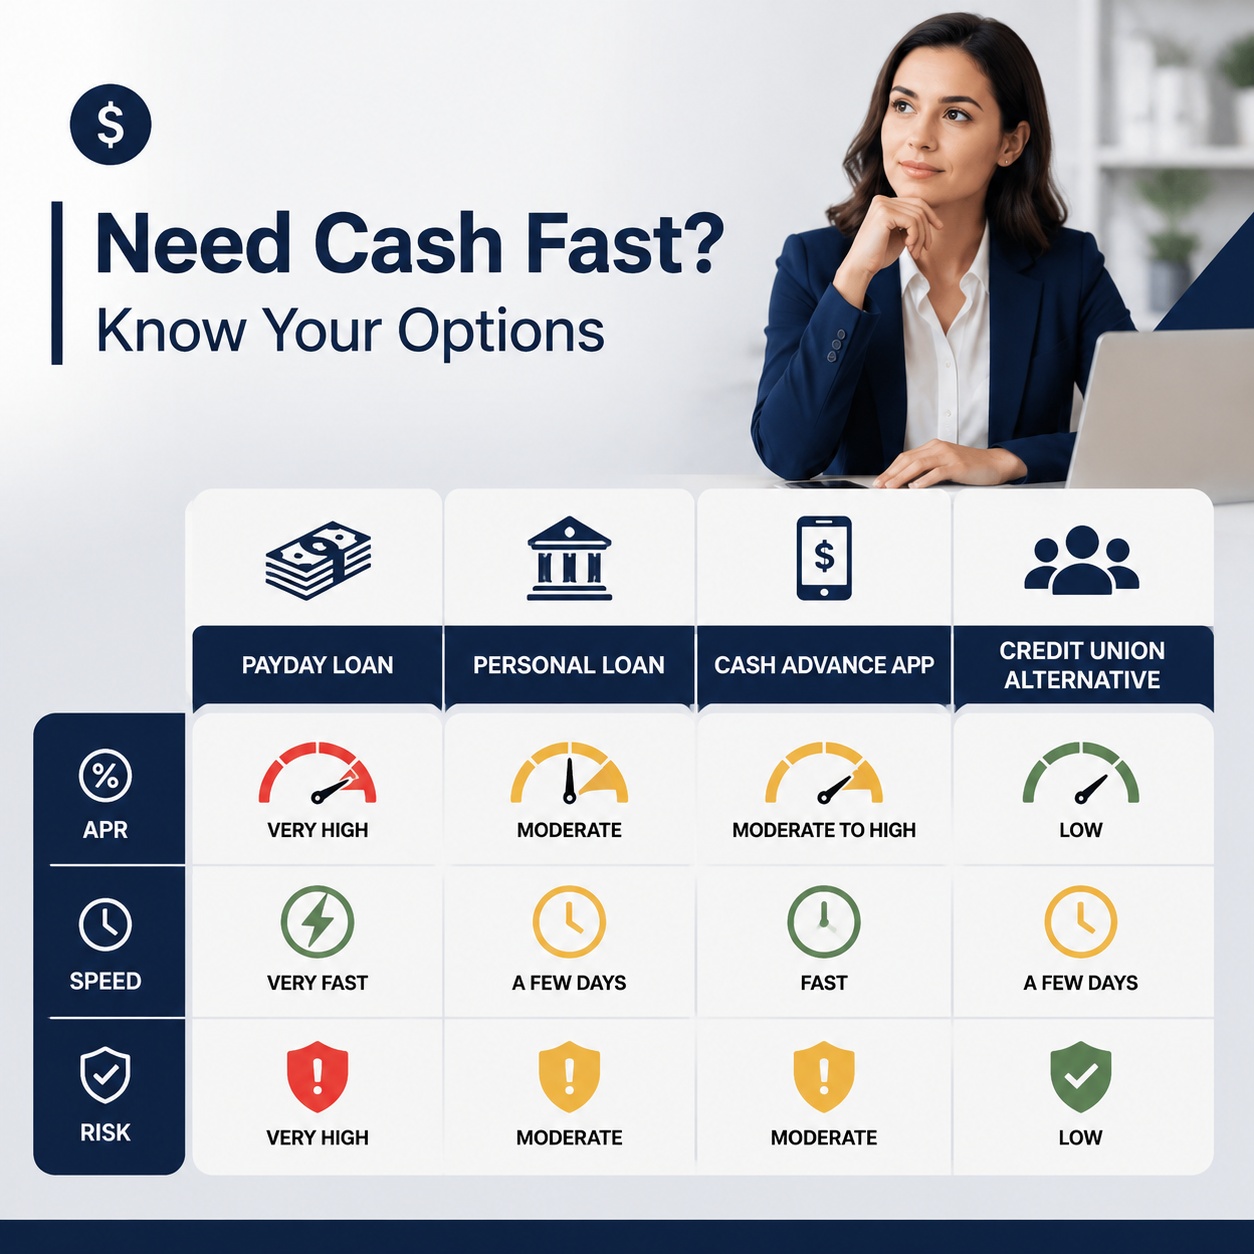
The $64,000 question: if payday loans cost so much, why do people use them? Simple. They’re fast and accessible. But there are other ways to cover short-term borrowing needs, so let’s talk options.
1. Payday Loans
The good: You can usually get cash within 24 hours, even with no credit check.
The bad: Those triple-digit APRs can make even a small loan feel monstrous once repayment hits. Plus, short loan terms (think two to four weeks) can leave you scrambling to pay it off just as your next bills are due.
2. Cash Advance Apps
Ever heard of Earnin or Dave? These apps let you borrow small sums against your next paycheck—often $50 to $500—with no traditional interest. Yay! But here’s the catch: they usually charge “tips” or fees that can add up. For example, the Center for Responsible Lending calculated the average APR on these apps to be 367%. So yeah… not exactly free money.
3. Credit Union Payday Alternative Loans (PALs)
If you belong to a credit union, check out their PAL options. Unlike payday lenders, credit unions cap interest rates at 28% for these loans—and they give you a longer repayment period of 1 to 6 months. Plus, they report payments to credit bureaus, which could help build your credit.
4. Personal Loans for Bad Credit
It might surprise you, but some online lenders like Avant or OneMain Financial approve borrowers with scores as low as 550. Interest rates won’t be as crazy as payday loans—they usually fall between 7% and 36% APR, depending on your credit. These loans take a little more time to process and often require a steady income, but they’re far less likely to trap you in a cycle of debt.
5. Pawnshop Loans
Got something valuable lying around—jewelry, a gaming console, or maybe a mint-condition bicycle? Pawnshops can lend you cash against its value. Sure, you risk losing the item if you can’t pay the loan back, but it’s better than pledging your entire paycheck.
Why Payday Loan APRs Hit Harder Than They Look
So, what makes a payday loan so expensive? It’s all in how the math plays out. APR (Annual Percentage Rate) considers the total cost of borrowing, including fees, over a year. Sounds boring, I know—who cares about a year, when you just need $300 today to fix your brakes?
But let me show you why this matters. Say you grab a $300 payday loan to cover that car repair. The lender charges you a $45 fee for the two-week loan. That might not sound terrible—until you calculate the APR. Here’s how it breaks down:
- Loan amount = $300
- Fee = $45
- Loan term = 14 days
The APR? 391%. Yikes. And that’s for a single two-week cycle. What happens if you can’t repay the loan in full and roll it over? Those fees stack up quick, and suddenly you’re paying $90, then $135, then $180… you get the idea.
This is where payday loans can catch people in a trap—rolling over balances repeatedly until they owe more in fees than they borrowed in the first place. Remember the hot dog example? Imagine now you’re on your fourth $20 hot dog, and you’re three bites away from bankruptcy. Not ideal.
How to Spot a Legit Lender
Here’s a truth I’ve learned in my years of writing about lending: where there’s fast money, there are always people looking to take advantage of others. Payday lending can be a minefield of scams and shady operators, so you need to do a little homework before you hit “apply.”
Start by checking for state licensing. In the U.S., payday loans are regulated on a state-by-state basis, which means the loan terms (and even whether payday loans are legal) can vary wildly. For example, payday loans are capped at $500 in Washington State—but in California, there are no hard-and-fast limits.
Next, read up on the lender’s reputation. Look for Better Business Bureau (BBB) ratings and reviews from actual customers. If someone had a bad time, they’re probably shouting about it online. Beware of lenders that promise “guaranteed approval” or avoid laying out the full cost of your loan upfront—that’s an immediate red flag.
Avoiding the Debt Spiral
Payday loans might be there for emergencies, but let’s not make them a habit. If you keep turning to short-term borrowing just to make ends meet, it’s probably time to rethink your budget (ugh, I know). And honestly, even some safer alternatives can work wonders if you think about them early:
- Emergency Savings: Yeah, I’m going to be “that person” for a sec. Even stashing $20 a week could mean $520 by the end of the year—enough to help dodge future payday loans.
- Nonprofit Assistance: Look into local charities or community organizations that offer emergency help for rent, utilities, or food. Many are happy to help once you explain your situation.
- Hardship Programs: Got existing loans or bills you’re struggling with? Call your lender, credit card company, or service provider and ask about payment plans or deferrals. You’d be amazed how often they say yes.
And if you do need to rebuild credit, choose financing options that report on-time payments to the credit bureaus. Some lenders, including credit unions and bad-credit personal loan companies, can help turn an emergency loan into a step toward financial recovery.
The Bottom Line on Viva Payday Loans
Viva Payday Loans and other bad credit payday loan options fill a very real need—getting cash when traditional lenders turn their backs. For the right borrower, they can work as a short-term cash solution, especially with their same day funding options.
But let’s be real. Payday loans aren’t anyone’s dream scenario. They’re a tool for emergencies, not a lifestyle. The key is understanding what you’re signing up for, comparing options, and making the decision that saves you the most stress (and money) in the long run. If payday loans are your only option right now, fine—but don’t stop there. Use it as a stepping stone to a better financial situation.
And next time, let’s aim for that $5 hot dog instead of the fancy $20 one, yeah? It’s the little changes that stack up.

